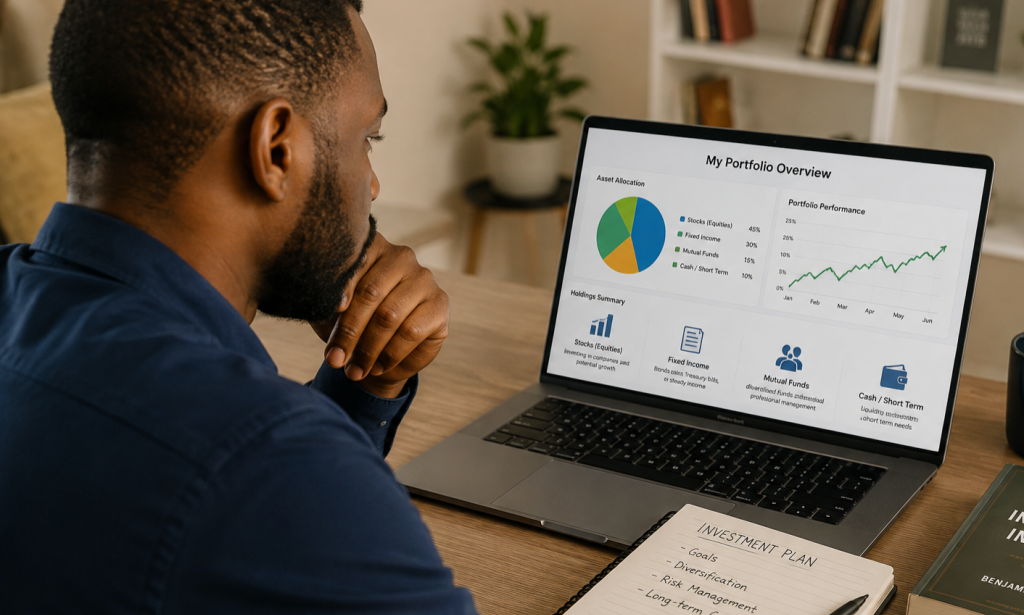
If you put all your money into one investment, your financial future can become heavily dependent on what happens to that one investment.
If it performs well, you may benefit significantly.
If it performs badly, your entire portfolio can suffer.
This is where investment diversification comes in.
Diversification means spreading your money across different investments so that your financial results don't depend entirely on one asset, company, sector or type of investment.
It doesn't guarantee that you won't lose money.
It also doesn't mean buying as many investments as possible.
The goal is simpler:
Don't allow one investment to determine the outcome of your entire portfolio.
The Securities and Exchange Commission (SEC) Nigeria identifies diversification as an important investment strategy and recommends spreading investments across different asset classes, industries and geographical regions to help reduce risk.
What Is Investment Diversification?
Investment diversification is the practice of spreading your investments across different assets or investments rather than concentrating everything in one place.
For example, imagine someone has:
₦1 million
and puts the entire amount into shares of one company.
That person has concentrated risk.
If the company's share price falls sharply, a large portion of the investor's portfolio falls with it.
Now imagine another investor has ₦1 million spread across several appropriate investments.
The poor performance of one investment may still hurt, but it may not have the same effect on the entire portfolio.
That's the basic idea behind diversification.
Why Does Diversification Matter?
Investments behave differently.
A particular stock may fall while government securities remain relatively stable.
One industry may struggle while another performs well.
One asset class may perform poorly during a particular period while another performs better.
Because you cannot know exactly which investment will perform best in advance, diversification can reduce your dependence on a single outcome.
It is one reason the SEC advises investors to diversify across asset classes and industries.
Diversification Does Not Mean Guaranteed Profit
This is important.
A diversified portfolio can still lose money.
Imagine you own:
- Nigerian stocks
- A mutual fund
- Government securities
- Another investment
If the overall market experiences a difficult period, several parts of the portfolio could fall at the same time.
Diversification reduces concentration risk.
It does not eliminate investment risk.
You can still lose money.
A Simple Example
Suppose you have:
₦1 million
Option A: Concentrated portfolio
₦1,000,000 → One stock
If that stock falls 30%, the investment could fall to approximately:
₦700,000
before considering other factors.
Option B: Diversified portfolio
For illustration only:
₦300,000 → Stocks
₦300,000 → Fixed-income investment
₦250,000 → Mutual fund
₦150,000 → Other suitable investment
If one part performs badly, the effect on the entire portfolio may be smaller.
But this isn't automatically a better portfolio.
The exact mix should depend on the investor's goals, time horizon, risk tolerance and the characteristics of the investments.
Diversification Can Happen at Different Levels
Many people think diversification simply means buying several stocks.
It's broader than that.
You can diversify across:
Asset classes
Companies
Industries
Geographies
Investment periods
And sometimes even currencies, depending on your objectives and circumstances.
Diversifying Across Asset Classes
One of the most important forms of diversification is spreading money across different types of assets.
For example, a portfolio might contain some combination of:
- Stocks
- Bonds
- Government securities
- Mutual funds
- Cash or savings
- Other suitable investments
The SEC identifies equities, fixed-income securities, mutual funds, ETFs and other products among the investment opportunities available in the Nigerian capital market.
Different assets can have different risk and return characteristics.
Diversifying Across Companies
Suppose you want to invest in stocks.
Buying shares in just one company creates concentration risk.
If you instead own shares in several companies, problems affecting one company may have a smaller effect on your overall portfolio.
However, owning 10 companies doesn't automatically mean you're well diversified.
If all 10 companies operate in the same industry, you could still have significant concentration.
Diversifying Across Industries
Consider someone who invests entirely in banking stocks.
They may own five different banks.
That looks diversified at first.
But all five investments are still exposed to developments affecting the banking sector.
If the entire sector faces serious difficulties, several holdings could be affected at the same time.
A portfolio spread across different industries may have less sector concentration.
Diversifying Through Mutual Funds
You don't always need to choose dozens of individual investments yourself.
A mutual fund or other collective investment scheme can pool money from multiple investors and invest according to the fund's mandate.
SEC Nigeria explains that unit trusts pool money from investors and can provide diversification and professional management.
This can make diversification more accessible to people who don't want to build an entire portfolio of individual securities themselves.
But remember:
A mutual fund is not automatically diversified just because it is a fund.
You still need to understand what the fund invests in.
A fund concentrated in one sector or asset class may still carry significant concentration risk.
Diversification Within a Bond Portfolio
Diversification also matters with fixed-income investments.
For example, investors can consider differences in:
- Issuer
- Maturity
- Interest rate
- Credit risk
- Type of security
SEC Nigeria notes that bonds can also be packaged into collective investment schemes, allowing investors to access a diversified selection through a bond fund.
How Much Diversification Do You Need?
There is no universal number.
You don't need to own:
50 stocks + 10 mutual funds + 20 bonds
just to call yourself diversified.
In fact, owning too many investments can create another problem:
You may not understand what you actually own.
A smaller portfolio of investments that serve clear purposes can be better than a huge collection of random assets.
Over-Diversification Is Possible
Imagine someone has:
- 25 individual stocks
- 10 mutual funds
- 8 ETFs
- Several government securities
- Multiple savings products
It may look impressive.
But some of those investments could own many of the same companies.
For example, you could own a bank stock directly while also holding several funds that contain that same bank.
You may therefore have more exposure to the company than you realize.
Diversification isn't about counting investments.
It's about understanding your actual exposure.
The Difference Between Diversification and Asset Allocation
These two concepts are related but not identical.
Asset allocation is how you divide your portfolio among different types of investments.
For example:
50% equities
30% fixed income
20% other assets
Diversification is then about spreading exposure within those categories.
For example, if the 50% allocated to equities is spread across different companies and industries, you're diversifying within that allocation.
A good portfolio considers both.
Your Age Can Matter, But It Isn't the Only Factor
You may hear advice such as:
“Young investors should own more stocks.”
There is some logic behind this because younger investors may have longer time horizons.
But age alone shouldn't determine your portfolio.
You should also consider:
- Your goals
- Your income
- Your emergency fund
- Your financial obligations
- Your investment horizon
- Your ability to tolerate losses
- Your risk capacity
The SEC specifically advises investors to understand their risk tolerance and choose investments that align with their risk profile.
Risk Tolerance vs Risk Capacity
These are worth separating.
Risk tolerance
This is how comfortable you are with investment losses or volatility.
Risk capacity
This is how much financial loss you can realistically afford.
You might be emotionally comfortable with a 30% decline.
But if you need the money for school fees in three months, you may not have the financial capacity to take that risk.
That's why diversification should be connected to your actual financial situation.
Your Investment Time Horizon Matters
Consider two investors.
Investor A
Needs the money in six months.
Investor B
Won't need the money for 20 years.
They shouldn't necessarily have the same portfolio.
The second investor may have more ability to tolerate short-term market fluctuations.
The first investor has a much shorter time horizon.
Before deciding how to diversify, ask:
When will I need this money?
Don't Diversify Your Emergency Fund Into Risky Investments
Your emergency fund has a different job.
Its purpose is to provide accessible money when something unexpected happens.
You shouldn't necessarily treat your emergency fund as part of your long-term investment portfolio.
MoneyTrut previously covered emergency savings in How Much Should You Have in an Emergency Fund?.
Keeping your emergency reserve separate can make it easier to leave long-term investments alone when markets are falling.
Diversification and Inflation
Diversification can also help you think beyond simply keeping money in cash.
If all your long-term wealth is held in cash, inflation can reduce its purchasing power over time.
Different investments may respond differently to inflation and economic conditions.
But that doesn't mean you should invest everything.
The right balance depends on your goals and circumstances.
Diversification Doesn't Mean Avoiding Losses
Imagine you own 10 stocks.
If the entire stock market falls, your portfolio could still decline.
You may be diversified within stocks, but not diversified across asset classes.
This is why diversification can happen at several levels.
For example:
One company → concentrated
Several companies → more diversified
Several industries → broader diversification
Several asset classes → broader still
But broader isn't automatically better.
The portfolio still needs to make sense for you.
A Simple Example for a Beginner
Suppose you have:
₦500,000
available for long-term investment.
Instead of immediately choosing one stock because someone recommended it, you could first decide what the money is supposed to accomplish.
Maybe you want:
- Some growth
- Some stability
- Some liquidity
You could then research investments that serve those purposes.
The final allocation might be very different for another person.
That's okay.
Diversification should support the investor's goals rather than become a mathematical exercise.
What If You Only Have ₦10,000 to Invest?
You might think diversification is impossible with a small amount.
Not necessarily.
Depending on the investment product, minimum investment amounts and available options, you may be able to gain diversified exposure through a collective investment scheme rather than buying many individual securities.
SEC Nigeria explains that unit trusts allow investors to pool money into a portfolio managed on their behalf.
This is one reason understanding investment products can be more useful than simply trying to copy someone else's portfolio.
What If You Have ₦100,000?
With ₦100,000, you don't need to create a complicated portfolio.
Your priority should be understanding:
What am I investing for?
How long can the money stay invested?
How much risk can I take?
What are the fees?
Who manages the investment?
Is the operator properly registered?
Those questions can be more important than owning a particular number of assets.
What If You Have ₦1 Million?
With ₦1 million, concentration becomes more important to think about.
Putting the entire amount into one highly volatile investment could expose you to substantial losses.
A diversified approach may spread the risk across appropriate investments.
But again, diversification doesn't mean randomly buying everything available.
You should have a reason for each part of the portfolio.
What If You Have ₦5 Million?
At ₦5 million, portfolio structure becomes even more important.
You may have exposure to several asset classes, but you should still understand:
- How much is invested in each asset
- What percentage is exposed to equities
- What percentage is in fixed income
- How much can be accessed quickly
- How much is exposed to one company
- How much is exposed to one industry
- What fees you're paying
The larger the portfolio becomes, the more important it can be to understand concentration.
Check Your Portfolio for Hidden Concentration
This is something many investors overlook.
Suppose you own:
Stock A directly
and also own:
Fund B
which has a large allocation to Stock A.
You might think you have two investments.
But economically, you're still heavily exposed to Stock A.
The same can happen across industries.
Understanding what your funds actually own is therefore important.
Diversification Doesn't Mean You Should Chase Foreign Investments
Geographical diversification can have benefits.
But you shouldn't invest internationally simply because someone says:
“Nigeria is risky, so put everything abroad.”
Foreign investments come with their own risks, including:
- Currency movements
- Foreign market volatility
- Fees
- Tax considerations
- Regulatory differences
- Access and liquidity considerations
Geographical diversification can be useful, but it needs to fit your financial plan.
Rebalancing Your Portfolio
Your portfolio can change over time even if you don't make any new investment decisions.
Suppose you start with:
50% equities
50% fixed income
If equities perform strongly, your portfolio might eventually become:
70% equities
30% fixed income
Your portfolio has become riskier relative to where you started.
Rebalancing means reviewing the portfolio and, where appropriate, adjusting it back toward your intended allocation.
The appropriate frequency depends on your strategy.
You don't necessarily need to rebalance every month.
Don't Rebalance Just Because the Market Moved
A market decline doesn't automatically mean you should sell.
A market increase doesn't automatically mean you should buy.
Rebalancing should be connected to your investment plan.
This is another reason to establish your allocation before emotions take over.
Diversification and Compound Growth Work Together
Your previous MoneyTrut article on compound interest explains why time and reinvested returns can contribute to long-term growth.
Diversification addresses a different problem.
Compounding helps explain how wealth can grow.
Diversification helps manage concentration risk.
You need to think about both.
A portfolio can be diversified and still have poor returns.
A concentrated investment can produce enormous returns—or enormous losses.
The objective is to build a portfolio that gives you a reasonable chance of reaching your financial goals without taking risks you cannot afford.
Be Careful With Investment Platforms Promising Guaranteed Returns
Diversification doesn't protect you from fraud.
You could diversify your money across several legitimate investments and still lose money if you put a large amount into an unregistered investment scheme.
The SEC warned in May 2026 about unregistered online investment schemes promoted through platforms including WhatsApp, Instagram, Telegram, Facebook and TikTok, particularly schemes promising unrealistic or guaranteed returns.
Before investing, verify the operator.
The SEC's investor portal provides resources for checking registered operators and tracking investor-related notices.
A Simple Diversification Checklist
Before investing, ask:
1. What is my goal?
Why am I investing?
2. When will I need the money?
Six months, five years or 20 years?
3. What is my risk tolerance?
How comfortable am I with fluctuations?
4. What is my risk capacity?
How much loss can I actually afford?
5. What assets do I own?
Stocks, bonds, funds, cash and others?
6. Am I too concentrated?
Is one company, sector or asset responsible for too much of my portfolio?
7. What fees am I paying?
Costs reduce the money available to compound.
8. Is the investment provider properly regulated?
Verify before sending money.
9. Do I understand what I'm buying?
If you can't explain the investment simply, learn more before committing money.
The Bottom Line
Investment diversification is not about owning as many investments as possible.
It's about avoiding unnecessary concentration and building a portfolio where one investment, company, sector or asset doesn't determine your entire financial outcome.
A beginner with ₦10,000 may use a very different approach from someone investing ₦1 million or ₦5 million.
That's perfectly normal.
Start with your goal.
Understand your time horizon and risk.
Choose appropriate investments.
Then diversify in a way that actually makes sense for your situation.
And remember:
Diversification cannot guarantee that you won't lose money. It is simply one of the tools investors can use to manage concentration risk.
You must be logged in to post a comment.