A budget is supposed to tell you where your money should go before you spend it.
But for many people, budgeting becomes a monthly exercise that looks good on paper and falls apart within a week.
You write down your salary.
You assign amounts to rent, food, transportation and savings.
Then an unexpected expense appears.
A family member needs help.
Your electricity bill is higher than expected.
Transport costs increase.
You spend more on food.
Before the month is over, the budget is already wrong.
That does not necessarily mean budgeting does not work.
It may mean the budget was built around an ideal version of your life instead of your actual spending.
A useful budget should do something much simpler:
It should help you understand where your money is going, decide what matters most and make sure you don't spend money you have already committed to something else.
What Is a Monthly Budget?
A monthly budget is simply a plan for your income and expenses.
You estimate:
- how much money will come in
- what you need to spend
- what you want to spend
- what you need to save
- what debts you need to repay
- what financial goals you are working toward
A budget does not have to be complicated.
In fact, if your budgeting system is so complicated that you stop using it after two weeks, it is probably too complicated.
Step 1: Start With Your Actual Income
The first number in your budget is the money you actually expect to receive.
If your monthly take-home income is ₦500,000, start with ₦500,000.
If your income changes from month to month, don't automatically budget based on your best month.
For example, suppose your income over four months was:
- January: ₦420,000
- February: ₦510,000
- March: ₦460,000
- April: ₦550,000
If your income is unpredictable, using ₦550,000 as your normal monthly income could create problems.
A safer approach may be to build your basic budget around a more conservative income figure and treat unusually high income as extra money to allocate toward savings, debt or other goals.
The exact approach depends on how predictable your income is.
Step 2: Find Out Where Your Money Is Actually Going
This is where many budgets go wrong.
People guess.
They think they spend about ₦60,000 on food.
Maybe they spend ₦90,000.
They think transport costs ₦30,000.
Maybe it is ₦50,000.
They forget subscriptions, transfers, small purchases, bank charges and occasional expenses.
Before building a serious budget, spend at least one month studying your actual spending.
If you already have access to several months of transaction history, even better.
Look at:
- bank statements
- mobile-money transactions
- card transactions
- cash spending
- transfers
- subscriptions
- bills
- food purchases
- transportation
- family support
- debt payments
You may discover that your spending habits are very different from what you assumed.
Step 3: Separate Needs From Wants
This does not mean that every “want” is bad.

It means you should know the difference.
Needs
These are expenses you generally need to maintain your basic life and responsibilities.
Examples might include:
- housing
- basic food
- transportation
- electricity
- water
- healthcare
- essential communication
- minimum debt payments
- necessary family obligations
Wants
These are expenses that improve your lifestyle but could potentially be reduced, postponed or removed.
Examples might include:
- eating out
- entertainment
- expensive subscriptions
- unnecessary shopping
- frequent deliveries
- upgrades you don't need
- some leisure activities
The distinction isn't always perfect.
For example, internet access may be essential for someone working online but discretionary for someone else.
The important question is:
If my income dropped suddenly, which expenses would I absolutely need to keep paying?
That question helps you identify your true essential expenses.
Step 4: Calculate Your Fixed Expenses
Fixed expenses are costs that are relatively predictable.
For example:
| Expense | Monthly amount |
|---|---|
| Rent allocation | ₦100,000 |
| School fees allocation | ₦40,000 |
| Loan payment | ₦30,000 |
| Insurance | ₦10,000 |
| Internet | ₦15,000 |
| Total | ₦195,000 |
Not every expense will be exactly the same every month.
But these are costs you can usually anticipate.
Knowing your fixed expenses tells you how much of your income is already committed before you start spending on variable costs.
Step 5: Don't Forget Annual Expenses
This is one of the biggest weaknesses in many monthly budgets.
Something that happens once a year can still be part of your monthly financial reality.
For example, suppose your annual rent is ₦1.2 million.
Instead of pretending rent costs nothing for eleven months and then suddenly costs ₦1.2 million, you can treat it as:
₦1.2 million ÷ 12 = ₦100,000 per month
You could set aside ₦100,000 every month toward the future rent payment.
The same idea can apply to predictable expenses such as:
- school fees
- annual insurance
- professional fees
- vehicle registration
- maintenance
- annual subscriptions
- major family obligations
These are sometimes called sinking funds.
The principle is simple:
If you know an expense is coming, start preparing for it before it arrives.
Step 6: Estimate Variable Expenses
Some expenses change from month to month.
For example:
- food
- transportation
- electricity
- entertainment
- household purchases
- personal spending
Don't pretend you can predict these perfectly.
Instead, use your previous spending to create realistic limits.
Suppose your food spending over the last three months was:
₦75,000
₦82,000
₦78,000
Setting a budget of ₦50,000 may look disciplined, but if you consistently spend around ₦78,000, you are likely to exceed your budget.
A better starting point might be ₦80,000.
Once you understand your actual spending, you can work on reducing it if necessary.
A realistic budget is more useful than an impressive budget you constantly break.
Step 7: Give Savings a Place in the Budget
Savings should not simply be:
“Whatever is left at the end of the month.”
That approach often produces nothing.
If your income is ₦500,000 and you want to save ₦75,000, put it into the budget before discretionary spending.
For example:
| Category | Amount |
|---|---|
| Income | ₦500,000 |
| Essential expenses | ₦300,000 |
| Emergency savings | ₦75,000 |
| Long-term investment | ₦50,000 |
| Discretionary spending | ₦50,000 |
| Buffer | ₦25,000 |
| Total | ₦500,000 |
This is a hypothetical example, not a universal formula.
Someone else may need ₦350,000 for essential expenses and have much less available for savings.
The important principle is:
Give savings a defined amount and purpose instead of hoping money will remain at the end of the month.
If your income is limited and you are struggling to start an emergency fund, see our guide on How to Build an Emergency Fund With a Low Income. If you want to understand how much you may need to set aside for unexpected expenses, read How Much Should You Have in an Emergency Fund?.
Step 8: Create a Buffer
A budget with no margin is fragile.
Suppose you assign every ₦500,000 of your income to specific expenses.
Then your electricity bill is unexpectedly higher.
Or your child needs medication.
Or your car requires a repair.
If there is no flexibility in your budget, you may have to take money from savings or borrow.
A small monthly buffer can help.
For example:
₦25,000–₦50,000
could remain available for genuinely unexpected or irregular expenses.
If you don't use it, you can move it into savings or another financial goal at the end of the month.
The amount depends entirely on your income and circumstances.
Step 9: Budget for Family Support
This deserves special attention in a Nigerian budget.
Many people financially support:
- parents
- siblings
- children
- extended family
- relatives dealing with emergencies
Pretending these payments do not exist will produce an unrealistic budget.
If you regularly send ₦40,000 to family members, include it.
If you regularly contribute ₦20,000 toward a parent's expenses, include it.
The purpose of a budget is not to judge your spending.
It is to reveal your actual financial commitments.
If family support is putting pressure on your finances, the budget can also help you see how much you are realistically able to provide.
Step 10: Deal With Debt Before It Controls Your Budget
Debt payments can consume a significant part of monthly income.
List each debt separately.
For example:
| Debt | Monthly payment |
|---|---|
| Personal loan | ₦50,000 |
| Credit balance | ₦30,000 |
| Other loan | ₦20,000 |
| Total | ₦100,000 |
Now you know that ₦100,000 of your monthly income is already committed to debt payments.
This makes it easier to see why saving ₦150,000 every month may not be realistic.
If you have expensive debt, reducing that debt can become one of your major financial priorities.
Don't simply look at the monthly payment.
Pay attention to the interest rate, outstanding balance, fees and remaining term.
A small monthly payment can still represent an expensive debt if it lasts for a long time or carries a high interest rate.
Step 11: Use a Budgeting Method That You Can Actually Maintain
There are many budgeting systems.
You do not need to follow a particular method just because it is popular online.
Zero-based budgeting
You assign every unit of income a purpose.
If you earn ₦500,000, your planned allocations should total ₦500,000.
That does not mean you must spend all ₦500,000.
Savings and investments are also allocations.
Percentage-based budgeting
You divide income into percentages.
For example:
- 60% essentials
- 20% savings
- 10% investing
- 10% discretionary spending
This can be a useful starting framework.
But don't force your actual life into percentages that don't fit.
Simple category budgeting
You can also keep it extremely simple:
Needs
Savings/debt
Wants
This may be enough for someone who wants a straightforward system.
The best method is the one you will actually use.
Step 12: Budget Before the Month Starts
Don't wait until the month is almost finished.
Before receiving your salary—or as soon as you receive it—decide what the money needs to accomplish.
For example:
₦500,000 income
↓
₦300,000 essential expenses
↓
₦75,000 emergency savings
↓
₦50,000 investing
↓
₦50,000 discretionary spending
↓
₦25,000 buffer
Now you have a plan.
Without that plan, the money may simply disappear into dozens of small decisions.
Step 13: Track Your Budget During the Month
Creating a budget once is not enough.
You need to compare your plan with reality.
If you budget ₦50,000 for discretionary spending and have already spent ₦45,000 by the 15th, that is useful information.
You can adjust your behavior before the month ends.
The budget becomes a feedback system, not just a document.
Step 14: Review Your Budget Every Week
You don't need to spend an hour doing this.
Once a week, check:
How much have I spent?
How much is left?
Did anything unexpected happen?
Am I still on track with savings?
Are any bills coming up?
A short weekly review can prevent a small spending problem from becoming a major end-of-month problem.
Step 15: Adjust the Budget When Reality Changes
A budget is not a contract with yourself that can never change.
If your rent increases, update it.
If your salary increases, update it.
If you lose income, update it.
If your family situation changes, update it.
If transportation becomes more expensive, update it.
A budget that cannot adapt is not a useful budget.
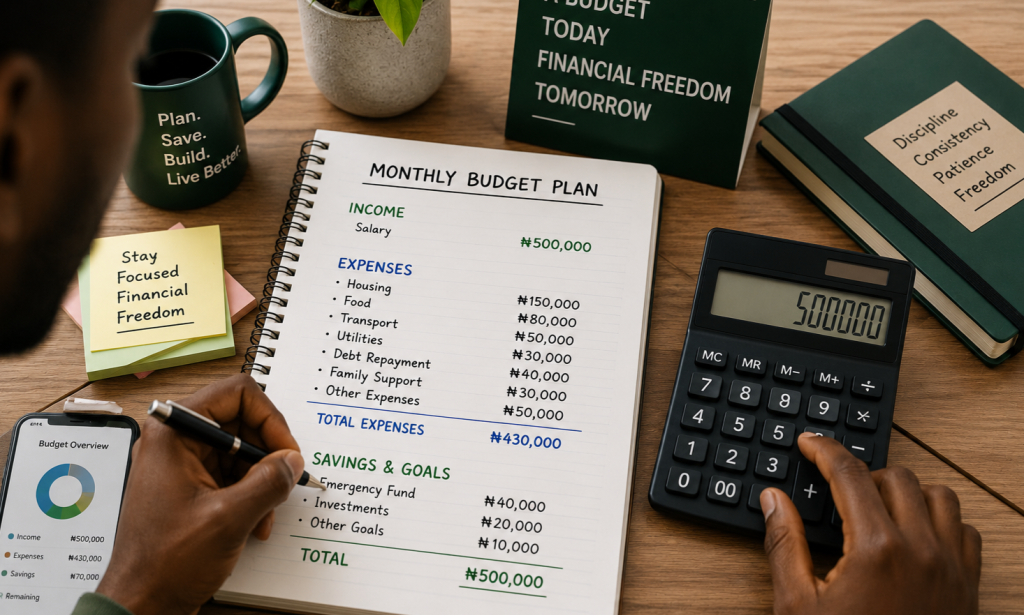
A Practical ₦500,000 Monthly Budget
Let's put everything together.

Imagine someone earning ₦500,000 per month.
If you earn ₦500,000 a month and want to understand how much you could realistically save, see How Much Should You Save From a ₦500,000 Salary?.
Their budget might look like this:
| Category | Amount | Purpose |
|---|---|---|
| Housing/rent allocation | ₦100,000 | Future housing cost |
| Food | ₦80,000 | Household food |
| Transportation | ₦45,000 | Work and essential travel |
| Utilities/communication | ₦30,000 | Electricity, water, phone, internet |
| Family support | ₦25,000 | Regular family obligation |
| Debt repayment | ₦20,000 | Minimum required payment |
| Emergency savings | ₦75,000 | Build financial buffer |
| Investing | ₦50,000 | Long-term financial goal |
| Personal spending | ₦50,000 | Discretionary |
| Buffer | ₦25,000 | Unexpected/irregular costs |
| Total | ₦500,000 |
Again, this is a hypothetical example.
If your rent is higher, your food costs are higher or you support several dependants, your numbers may look completely different.
The value of the example is the structure—not the exact amounts.
What If You Earn ₦100,000?
Budgeting is not only for people earning high salaries.
Suppose you earn ₦100,000.
Your budget could be:
| Category | Amount |
|---|---|
| Essential expenses | ₦70,000 |
| Savings/emergency fund | ₦10,000 |
| Debt repayment | ₦5,000 |
| Personal spending | ₦10,000 |
| Buffer | ₦5,000 |
| Total | ₦100,000 |
Again, these are illustrative numbers.
If your essential expenses already consume ₦90,000, saving ₦10,000 may not be realistic without making changes elsewhere.
But even a small planned saving amount can help establish the habit.
The goal is not to make a low-income household look like a high-income household on paper.
The goal is to give the available money a clear purpose.
What If You Earn ₦1 Million?
A higher income gives you more possibilities, but it does not automatically produce financial security.
Suppose someone earns ₦1 million but spends almost all of it every month.
They may be financially more vulnerable than someone earning ₦500,000 who consistently saves and has manageable expenses.
A hypothetical ₦1 million budget might allocate:
- ₦500,000 to essential expenses
- ₦150,000 to savings
- ₦150,000 to investments
- ₦100,000 to discretionary spending
- ₦100,000 to a combination of debt repayment, sinking funds and other goals
But again, the percentages are not the point.
The point is that higher income should ideally create financial margin, not simply higher consumption.
What If Your Income Changes Every Month?
If you are self-employed, freelance or paid through commissions, a fixed monthly budget may not work well.
Suppose your income is:
January: ₦350,000
February: ₦600,000
March: ₦420,000
April: ₦750,000
Don't build your essential lifestyle around the ₦750,000 month.
Consider creating a baseline budget based on a conservative income level.
Then, when income is higher than expected, direct the excess toward:
- emergency savings
- taxes where applicable
- debt
- investments
- upcoming large expenses
- business reserves
This can make irregular income much easier to manage.
Your Budget Should Have Different Jobs for Your Money
One of the easiest ways to understand a budget is to give your money different jobs.
Job 1: Survive
Housing, food, transportation, utilities and healthcare.
Job 2: Protect
Emergency savings and appropriate insurance.
Job 3: Reduce financial pressure
Debt repayment.
Job 4: Build the future
Investments and long-term savings.
Job 5: Live
Entertainment, hobbies, eating out and other discretionary spending.
A healthy budget does not necessarily eliminate Job 5.
It simply makes sure that “living today” doesn't consume all the money needed for “protecting tomorrow.”
The Most Common Budgeting Mistakes
1. Making a budget based on what you wish you spent
Use your actual spending as your starting point.
2. Forgetting irregular expenses
Annual rent, school fees, repairs and insurance still need to be funded.
3. Saving whatever is left
If savings are important, give them a defined place in the budget.
4. Ignoring small purchases
Small recurring expenses can become significant over time.
5. Having no buffer
A budget with zero flexibility can collapse after one unexpected expense.
6. Treating the budget as permanent
Your financial situation changes. Your budget should change too.
7. Making the system too complicated
If you need a spreadsheet with 70 categories to understand your finances, you may be making the process harder than necessary.
How to Know If Your Budget Is Working
A budget is probably doing its job if:
- you know where your money is going
- your important bills are covered
- you are consistently saving something
- your debt is under control or declining
- you can prepare for predictable large expenses
- you have some flexibility for unexpected costs
- you are not constantly running out of money before payday
You don't need to hit every target perfectly.
The purpose is to improve your financial control over time.
What If You Keep Going Over Budget?
Don't immediately conclude that you lack discipline.
Find out why.
Maybe your food budget is unrealistic.
Maybe transportation costs have changed.
Maybe you forgot annual expenses.
Maybe family support is larger than you originally estimated.
Maybe you are spending impulsively.
Maybe your income is simply insufficient for your current obligations.
Each problem requires a different solution.
A budget should help you identify the problem instead of simply telling you that you failed.
The Bottom Line
A good monthly budget is not about restricting every naira you spend.
It is about making your money intentional.
Start with your actual income.
Track your real spending.
Separate essential expenses from discretionary spending.
Account for annual and irregular expenses.
Give savings and debt repayment a defined place.
Keep a reasonable buffer.
Review your spending during the month.
And change the budget when your circumstances change.
You do not need a complicated spreadsheet.
You need a system you will actually use.
The best budget is not the one that looks perfect on the first day of the month.
It is the one that still helps you make better decisions on the 15th, the 25th and the day before payday.
You must be logged in to post a comment.